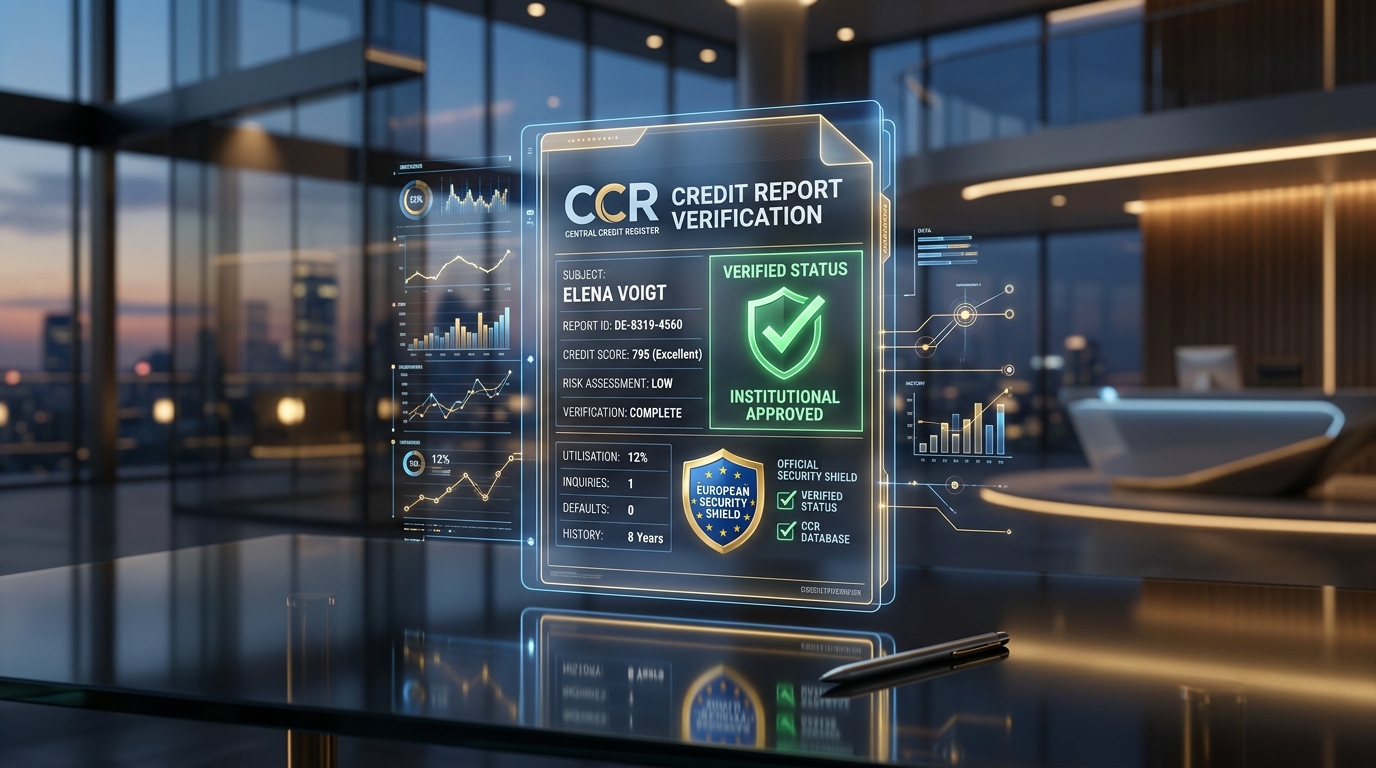
When applying for financing, lenders assess your past borrowing behavior and existing debt commitments. Knowing how these records are compiled enables you to anticipate committee criteria and polish your financial profile beforehand.
1. Central Credit Registers and Transparency
In many European countries (such as Portugal with the Central de Responsabilidades de Crédito managed by Banco de Portugal), financial institutions consult a centralized database recording all active loans and payment statuses.
2. The 3 Commitment Categories Analyzed
A. Effective Installment Loans
The outstanding capital on personal, auto, or mortgage loans currently being repaid through regular monthly schedules.
B. Potential Credit (Credit Cards & Overdrafts)
Approved credit limits you haven't drawn down. Banks often factor 3% to 5% of this authorized ceiling into your monthly debt burden, even if you owe nothing!
C. Overdue Payments (Default Alerts)
Missed monthly installments that remain unpaid. This red flag halts virtually any new credit approval.
3. 3 Practical Actions Before Submitting a Loan Request
Cancel idle credit cards
Close unused store cards and old credit lines to eliminate phantom debt capacity deductions.
Settle small overdrafts
Clear minor negative balances to present 3 consecutive months of clean, positive bank statements.
Avoid multiple hard pulls
Rely on independent simulations rather than submitting simultaneous bank inquiries that trigger alerts.